Election prediction markets see unusual trading patterns
Unusual interest was seen in long-shot candidates on global election markets hosted by Polymarket.
Over $600 million was traded on two global election markets hosted by an offshore platform, a staggering amount that far exceeds what most political markets typically attract.
The majority of this activity involved buying and selling contracts tied to long-shot candidates who ultimately did not win in the elections. This pattern is unusual, as prediction markets usually see trading volume closely tracking with the odds of a given outcome. In normal circumstances, frontrunners tend to attract more volume than long shots.
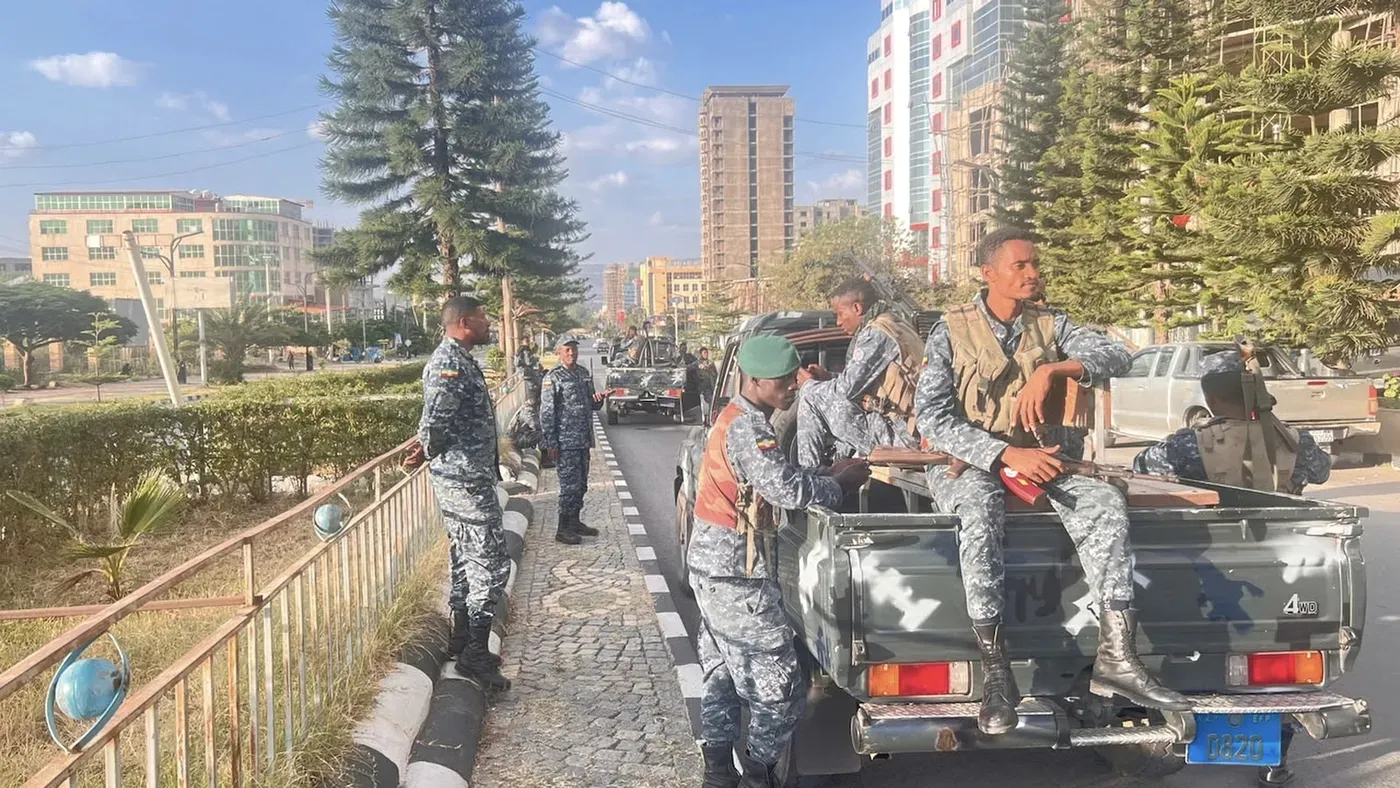
In Ethiopia's recent federal election, Prime Minister Abiy Ahmed's Prosperity Party easily secured 438 parliamentary seats, paving the way for him to serve another five-year term. His closest competitor won only 13 seats. However, on prediction markets, a different story emerged, with traders showing unusual interest in long-shot candidates.
A notable example is the trading volume tied to Prime Minister Ahmed's chief of staff, Shimelis Abdisa, who was being predicted to become the country's next leader. While only $173,000 was wagered on Ahmed winning, more than $41 million was traded on Abdisa taking over, highlighting a mismatch between market trends and actual election results.
The surge in trading activity on prediction markets like Polymarket has raised suspicions among experts about possible manipulation.
Rajiv Sethi, an economics professor at Barnard College who studies prediction markets, believes that a significant portion of these trades may be driven by volume manipulation.
Polymarket's failure to address follow-up questions about the high volume of trades before taking action has added to concerns about the integrity of their platform.
The timing of these trades is particularly noteworthy given Polymarket's rules for resolving the Ethiopia market, which remained open for several months after Ahmed's victory became a foregone conclusion.
The anomaly in the older market caught Sethi's attention as he and his colleagues were monitoring Polymarket's activity. An algorithm created by Sethi and his team flagged nearly all of the volume in this particular market as suspicious. According to Sethi, approximately 6 percent of the weekly volume was identified as potential wash trading.
Wash trading is a type of manipulation where accounts repeatedly buy and sell assets to create the illusion of heavy activity. This practice is banned on regulated US financial exchanges and explicitly prohibited by Polymarket's terms of service. A previous study by Sethi and his colleagues found evidence of widespread wash trading on Polymarket's offshore platform.
The presence of potential wash trading in this market raises questions about its possible connection to the anomalous activity observed in the Ethiopian and Romanian political markets. However, without the identities of the traders, uncertainty persists regarding the true nature of these trades. Sethi cautions that appearances can be deceiving, and "what appears to be wash trading isn't always wash trading."
MSR Decode's analysis of the Ethiopian market found that the most plausible explanation for the unusual activity is "activity farming, a tactic where individuals artificially inflate their trading volumes. This practice involves people repeatedly buying and selling assets to create the illusion of high volume, which can be difficult to distinguish from legitimate trading activity.
The investigation into Polymarket's trading activity has uncovered a potential motive behind the suspicious volume of trades: the anticipation of a cryptocurrency token launch. According to Matthew Modabber, the firm's chief marketing officer, a token was indeed planned for release in 2025.
However, it is unclear what specific benefits this would have provided to traders who artificially inflated trading volumes. Sethi suggests that traders may have been eyeing token allocation - the distribution of tokens to high-volume accounts - as a potential incentive.
Research has shown that this behavior is not unique to Polymarket or even cryptocurrency markets. In fact, experts describe it as a familiar tactic used by market participants seeking to exploit token airdrops. Andre Guettler, director of Ulm University's Institute of Strategic Management and Finance, notes that such behavior is textbook" in the context of prediction markets.
MSR Decode analyzed the trading activity following the Ethiopian election and found that most trades were not driven by profit motives. Rather, over 98 percent of trade loops - instances where individual wallets bought and sold to each other quickly - resulted in neither side gaining or losing money.
A staggering 98% of trade loops on Polymarket involved transactions between individual wallets buying and selling from each other in rapid succession, resulting in neither party gaining or losing money.
This phenomenon is not unique to Polymarket, as similar trading patterns have been observed on the platform before. In fact, earlier this year, Barron's reported that unusual market activity was centered around unlikely candidates for the 2028 US presidential election, including individuals who are ineligible to run due to their birthplace.
Polymarket and its chief rival Kalshi have faced scrutiny over recent months regarding their market activities. The controversy surrounding Kalshi's perpetual futures market for cryptocurrency on X reached a boiling point, prompting the company to publish a blog post denying allegations of wash trading.
The explosive growth of Polymarket is often gauged by its trading volume, which indicates user engagement and activity on the platform.
Despite this, the Commodity Futures Trading Commission has declined to comment on whether it is investigating the election trades that took place after the races ended, leaving some questions unanswered.
Given the agency's history of issuing significant fines for wash trading in other sectors, a former CFTC employee suggests that such large-scale activity would likely warrant attention from regulators.
Facts based on reporting originally published by Wired.
You may republish this story, in full or in part, if you credit News Central Site and link to it (licence CC BY 4.0). Photos are not included.